Net Worth Explained: How to Calculate & Track It
Financial Guidance Disclaimer
This article provides educational information only and does not constitute financial advice. Financial decisions should be based on your personal circumstances.
Current as of September 2026. Net worth statistics and the regulatory landscape around financial-data tools change over time — confirm current figures directly with the sources listed at the end of this guide.
Net Worth at a Glance
Aspect | What to Know |
|---|---|
What it measures | The value of everything you own minus everything you owe, as of one specific date |
How it's calculated | Total assets − total liabilities = net worth |
How often to check it | Commonly once or twice a year; checking too often can create noise from normal market swings rather than a meaningful trend |
Can it be negative? | Yes. Owing more than you own is common, especially early in adulthood or after taking on education debt |
How it differs from income | Income is money earned over a period of time; net worth is a snapshot of what has accumulated (or been paid down) as of today |
What Is Net Worth?
Net worth is the total value of everything a person or household owns (assets) minus everything they owe (liabilities), calculated as of a specific date. It is a snapshot of financial position, not a measure of income, cash flow, or overall financial health.
A few things follow directly from that definition. Net worth is not fixed — it changes as account balances move, asset values rise or fall, and debts are added or paid down, so any calculation is accurate only "as of" the date it was made. It is not the same as income: a high earner with significant debt and few assets can have a lower net worth than a modest earner who has saved consistently and paid down debt. Negative net worth — owing more than you own — is common, particularly for young adults, recent graduates, and people with student loans, and is not by itself a sign of financial trouble. And national average and median figures are frequently conflated in media coverage; because wealth is concentrated among a relatively small share of households, the average is typically much higher than the median, which better represents a "typical" household.
Net worth is a useful, directional indicator of financial progress — not a complete measure of financial security or personal worth. It leaves out job stability, health, insurance coverage, and future earning potential.
How Net Worth Is Actually Calculated
The formula is straightforward and doesn't require hedging:
Net Worth = Total Assets − Total Liabilities
To calculate it, list every asset you own at its current fair market value, list every liability you owe at its current outstanding balance, total each side, and subtract total liabilities from total assets. The result is a snapshot as of that specific date — not a permanent figure. It will change as balances move, debts shift, and asset values fluctuate, which is why financial professionals generally recommend tracking net worth as a trend across multiple points in time rather than reacting to any single calculation.
What You Need Before You Calculate It
A few practical checkpoints make the process transparent before you start:
Information: Recent statements or current balances for every account, debt, and major asset you hold.
Valuation: Value cash and account balances at their current statement amount; value investments and retirement accounts at current market value; value real estate, vehicles, and other property at a reasonable current fair market value, not the original purchase price; value debts at their current outstanding balance, not the original loan amount.
Scope: Decide whether you're calculating an individual figure or a combined household figure with a spouse or partner, and whether to include a business you own or track it on a separate business balance sheet.
Cadence: Most people recalculate quarterly or annually. Recalculating too often can create noise from normal market fluctuations rather than a meaningful trend.
Context: Treat the result as one data point in a broader financial picture, not a complete verdict on financial health.
The specific accounts, assets, and debts involved will vary by individual and household — this is the general process, not a fixed checklist.
Types of Net Worth
Gross assets vs. net worth. Gross assets are the total value of everything you own before subtracting debt. Net worth subtracts liabilities to show what you actually own free and clear. Someone can have substantial gross assets — an expensive home, for example — and still have a modest net worth once the mortgage is subtracted.
Total net worth vs. liquid net worth. Total net worth includes all assets, including illiquid ones like home equity and retirement accounts. Liquid net worth includes only cash and assets that could be accessed relatively quickly, such as checking, savings, and standard brokerage accounts, without a significant loss of value.
Example (illustrative): A homeowner's house has a current market value of $420,000, and the remaining mortgage balance is $260,000. Only the equity — $160,000 — counts toward net worth. The full $420,000 is listed as an asset, and the $260,000 mortgage is listed separately as a liability; the two figures net out to the equity amount.
Personal (individual) vs. household net worth. An individual's own assets and liabilities differ from a combined household figure. Most published statistics, including the Federal Reserve's Survey of Consumer Finances, report net worth at the household (family) level, so comparing your individual number directly to national statistics may not be an apples-to-apples comparison.
A business owner's or self-employed person's net worth. This is typically calculated by including the estimated value of an ownership stake as a personal asset while keeping the business's own operating balance sheet — its separate assets, revenue, and liabilities — conceptually distinct.
Example (illustrative): A small business owner estimates their ownership stake is worth $150,000, based on the business's own assets minus its debts, and includes that figure as a personal asset while keeping the company's day-to-day operating finances separate from their personal balance sheet. Business equity is inherently harder to price precisely than a bank balance or a publicly traded stock, since there's no daily market quote for it.
You may want to calculate more than one version — total net worth and liquid net worth, for instance — depending on the question you're trying to answer.
How to Actually Calculate Your Net Worth
Gather current statements or balances for every account and asset you hold.
List each asset at its current fair market value: cash, investments, retirement accounts, real estate, vehicles, business ownership, and other property.
List each liability at its current outstanding balance: mortgage, student loans, auto loans, credit card balances, and other debts.
Total all assets and total all liabilities separately.
Subtract total liabilities from total assets to arrive at net worth.
Record the date of the calculation.
Repeat at a regular interval — such as annually — to track the trend rather than relying on a single snapshot.
This process costs nothing. It can be done with a pen and paper, a spreadsheet, or a free template — no paid software or advisor is required to do the basic calculation.
Average and Median Net Worth by Age: What the Data Really Shows
The Federal Reserve's Survey of Consumer Finances (SCF) is conducted every three years by the Board of Governors of the Federal Reserve System and is widely considered the authoritative U.S. source on household wealth. The most recent completed edition collected data in 2022, and its findings were published by the Federal Reserve in October 2023 as "Changes in U.S. Family Finances from 2019 to 2022." The 2025 SCF is underway, and summary results are expected to be published in late 2026 — so at the time of this writing, the 2022 data remains the most current official figures. Check the Federal Reserve's SCF page directly for an updated release. 2025 Survey of Consumer Finances +3
According to that 2022 survey, median net worth across all U.S. families was $192,900, while mean (average) net worth was $1,063,700, both in 2022 dollars. The gap between the two is large because average net worth is pulled sharply upward by a relatively small number of very high-wealth households — the median is generally the more representative figure for a "typical" household.
Median vs. Average Net Worth by Age (2022 Survey of Consumer Finances)
Age of Reference Person | Median Net Worth | Average (Mean) Net Worth |
|---|---|---|
Under 35 | $39,000 | $183,500 |
35–44 | $135,600 | $549,600 |
45–54 | $247,200 | $975,800 |
55–64 | $364,500 | $1,566,900 |
65–74 | $409,900 | $1,794,600 |
75 or older | $335,600 | $1,624,100 |
Figures are household (family) level, in 2022 dollars, from the Federal Reserve's 2022 Survey of Consumer Finances. Values will be superseded once results from the 2025 SCF are published.
Example (illustrative): A 45-year-old sees a widely cited "average net worth" headline figure of roughly $1 million and feels behind. But that figure is a mean, skewed upward by a relatively small number of very high-net-worth households. Looking instead at the median for their age group — about $247,200, according to the same 2022 SCF — shows a very different, more representative comparison.
Separately, the Federal Reserve also publishes the Distributional Financial Accounts (DFA), which provide quarterly estimates of the distribution of U.S. household wealth, integrating Financial Accounts data with SCF microdata. The DFA is a distinct dataset from the SCF in methodology and update frequency — quarterly rather than triennial — and is updated on a rolling basis (most recently in September 2026). It's useful for tracking broad shifts in wealth concentration between SCF releases but doesn't replace the SCF's household-level detail on medians by age and other characteristics. The Fed - Distributional Financial Accounts Overview +2
Net Worth vs. Income, Savings, and Cash Flow
Term | What It Measures | How It Differs From Net Worth |
|---|---|---|
Income | Money earned over a period of time (salary, wages, business income) | Net worth is a stock (a snapshot at a point in time); income is a flow (measured over a period) |
Liquid net worth | Cash and easily accessed assets minus liabilities | A narrower subset of total net worth that excludes illiquid assets like home equity and retirement accounts |
Cash flow | Money moving in and out of your accounts over a period | Reflects short-term spending and earning; doesn't capture accumulated assets or debt |
Credit score | A numerical measure of creditworthiness based on borrowing and repayment history | Reflects debt behavior and repayment history, not the dollar value of what you own or owe |
Is a Negative Net Worth Normal?
Yes. Negative net worth simply means liabilities exceed assets, and it's common — particularly for young adults, recent graduates, and people carrying student loans or other education-related debt. It is not, by itself, a sign of financial trouble or poor money management.
Example (illustrative): A 24-year-old has $3,000 in checking and savings and a car worth $9,000 — $12,000 in assets. They also carry $28,000 in student loans and a $1,500 credit card balance — $29,500 in liabilities. Their net worth is -$17,500. For many people early in their careers, this is a normal, often temporary starting point that improves as income rises and debt is paid down, rather than a red flag on its own.
How to Increase Your Net Worth Over Time
Net worth generally grows through some combination of the following:
Paying down high-interest debt, which reduces liabilities directly
Building an emergency fund and consistently saving a portion of income
Contributing to retirement or investment accounts over time
Making extra payments toward loan principal (such as a mortgage) to build equity faster
Avoiding new debt that doesn't build an asset or your earning potential
Letting appreciating assets, like real estate or long-term investments, grow — though appreciation isn't guaranteed
Increasing income is one lever, but paying down debt and increasing savings also directly raise net worth, independent of a bigger paycheck.
Net Worth-Tracking Tools: Cost, Privacy, and Security
Cost. Calculating net worth itself is free. It requires no paid software, subscription, or advisor — a spreadsheet or a simple template works. Some net worth-tracking apps are free to use but generate revenue through advertising, data use, or by promoting paid financial products, which is worth understanding before linking accounts. Paid financial-planning tools or advisors may offer more personalized analysis, but that's a separate service from the basic act of calculating your number.
How account-aggregation works. Many tracking apps use account aggregation — technology that connects to your bank, credit card, and investment accounts to pull in balances automatically. This is generally more convenient than manual tracking, but it introduces data-sharing considerations a spreadsheet doesn't have. Before linking accounts, review a provider's privacy policy and security practices — such as whether it uses read-only, encrypted connections — and consider its reputation and how long it has operated.
The regulatory picture is still evolving. Consumers' rights regarding their own financial data are an active area of U.S. regulation. The Consumer Financial Protection Bureau finalized a rule in October 2024 (implementing Section 1033 of the Dodd-Frank Act) intended to give consumers a clearer right to share their financial data with third parties like aggregators and apps. That rule was scheduled to begin phasing in starting April 2026, but it has since become the subject of litigation and reconsideration by CFPB leadership. A federal court has enjoined enforcement of the rule while it is reconsidered, and the CFPB has been working on a replacement proposal as of this writing. In practical terms: don't assume any specific legal data-sharing right or requirement is currently settled or fully in effect. Verify the current status directly with the CFPB before relying on it. Access to Consumer Financial Data: Open Banking and the CFPB’s Section 1033 Rule | Congress.gov | Library of Congress +2
Cash and deposit safety. Separately, cash held at FDIC-insured banks (or NCUA-insured credit unions) is protected up to the standard coverage amount of $250,000 per depositor, per institution, per ownership category — a detail relevant to how you think about the safety of cash-type assets, distinct from net worth itself.
A word on sharing. Be cautious about publicly sharing specific net worth figures or detailed account information on social media. Doing so can attract social-engineering or scam attempts.
Common Mistakes When Calculating Net Worth
Valuing a home, car, or other property at its original purchase price instead of current fair market value.
Forgetting less obvious liabilities, such as a car loan, medical debt, or an outstanding 401(k) loan.
Counting a retirement account's full pre-tax balance without acknowledging that taxes will likely be owed on future withdrawals.
Confusing income or salary with net worth.
Comparing your results only to the "average" figure instead of the median, which better reflects a typical household.
Assuming one "good" net worth number applies at every age or income level.
Recalculating too frequently and over-reacting to normal, short-term market fluctuations.
Assigning an unreasonably optimistic value to hard-to-price assets like collectibles or business equity.
Forgetting to include liquid savings or checking account balances.
Double-counting jointly held assets or debts when combining two people's individual figures.
Leaving out debt entirely from a quick estimate, which overstates net worth.
Treating a growing net worth as a substitute for having emergency savings or adequate insurance coverage.
Reacting to a negative net worth without the context of how common it is early in a career or after additional education.
Linking financial accounts to a tracking app without reviewing its privacy or security practices first.
Using outdated account statements that no longer reflect current balances.
Common Misconceptions About Net Worth
Myth | Reality | Takeaway |
|---|---|---|
Net worth and income are the same thing | Income is earned over time; net worth is accumulated assets minus debts at a point in time | A high earner can have lower net worth than a consistent saver |
A higher salary always means higher net worth | Saving, spending, and debt habits matter just as much as income | Track your balance sheet, not just your paycheck |
Everyone the same age should have a similar net worth | Net worth varies widely by income, location, family situation, and life events | National age-based data is context, not a personal benchmark |
A home's full market value should be counted without subtracting the mortgage | Only home equity (value minus mortgage) adds to net worth | Always subtract what you still owe |
A negative net worth means someone is bad with money | It's common early in adulthood or after taking on education debt | Judge the trend over time, not one snapshot |
Net worth is a fixed number | It shifts constantly with market values, balances, and debt changes | Treat any calculation as accurate only "as of" that date |
The widely cited "average" net worth figure represents what's typical | The mean is skewed upward by a small number of very wealthy households | Use the median for a more representative comparison |
Only wealthy people need to think about net worth | The calculation is useful at any income or asset level | It works as a progress tracker regardless of starting point |
Retirement balances should be counted at full pre-tax value with no thought to future taxes | Withdrawals from traditional accounts are generally taxed, reducing real spendable value | Keep this in mind when interpreting your number |
A vehicle should be valued at its original purchase price | Vehicles are depreciating assets and should reflect current fair market value | Update vehicle values periodically |
All net worth calculators and apps are equally accurate and interchangeable | Tools vary in data sources, update frequency, and how they treat illiquid assets | Review how a tool calculates and sources its numbers |
Net worth includes only cash and investments | It also includes real estate, vehicles, retirement accounts, and business ownership | A complete list requires accounting for illiquid assets too |
Calculating net worth requires a financial advisor or specialized software | A pen, paper, or basic spreadsheet is enough | The math is simple; doing it regularly is what matters |
Net worth is the same as liquid savings available to spend immediately | Most net worth is often tied up in illiquid assets like home equity or retirement accounts | Don't assume your net worth reflects spendable cash |
Increasing income is the only way to grow net worth | Paying down debt and increasing savings also directly grow net worth | Multiple levers are available, not just a bigger paycheck |
Quick-Start Checklist: Am I Ready to Calculate My Net Worth?
Information question — Do I have current statements or balances for all my accounts, investments, and debts?
Scope question — Am I calculating my individual net worth or a combined household figure, and how will I treat a business I own, if any?
Valuation question — Do I have a reasonable way to value assets like my home, vehicle, or business at current fair market value rather than original purchase price?
Cadence question — How often will I recalculate my net worth so I can track a meaningful trend rather than reacting to short-term fluctuations?
This checklist is a starting point for your own calculation, not a substitute for individualized financial planning advice.
Glossary
Net worth — The total value of everything a person or household owns (assets) minus everything they owe (liabilities), calculated as of a specific date.
Assets — Anything of monetary value a person owns, such as cash, investments, retirement accounts, real estate, vehicles, and business ownership stakes.
Liabilities — Debts and financial obligations owed to others, such as a mortgage, student loans, auto loans, credit card balances, and personal loans.
Liquid net worth — A narrower measure including only cash and assets convertible to cash quickly without significant loss of value, excluding illiquid assets like home equity or retirement accounts.
Equity — The portion of an asset's value actually owned outright: current market value minus any debt owed against it, most often discussed as home equity.
Gross assets — The total value of everything owned, before subtracting any debt.
Fair market value — The price an asset would reasonably sell for in the current market, used instead of original purchase price.
Appreciating asset — An asset that tends to increase in value over time, such as real estate or many investments, though appreciation isn't guaranteed.
Depreciating asset — An asset that tends to lose value over time, such as a vehicle or most consumer electronics.
Median — The midpoint value when figures in a group are ranked from lowest to highest; half fall above it and half below.
Average (mean) — The total of all figures in a group divided by the number of figures; sensitive to a small number of very high or low values.
Survey of Consumer Finances (SCF) — A triennial survey by the Federal Reserve Board collecting detailed data on U.S. household assets, debts, and net worth.
Distributional Financial Accounts (DFA) — A Federal Reserve series providing quarterly estimates of how household wealth is distributed, distinct from the SCF in methodology and frequency.
Negative net worth — A financial position in which total liabilities exceed total assets, producing a net worth below zero.
Household net worth — The combined net worth of everyone in a household, such as spouses or partners.
Personal (individual) net worth — The net worth of one person's own assets and liabilities, calculated separately from a household total.
Account aggregation — Technology that connects to a person's bank, credit card, and investment accounts to automatically pull in balances, commonly used by net worth-tracking apps.
Frequently Asked Questions
What is net worth, and how is it calculated?
Net worth is the value of everything you own (assets) minus everything you owe (liabilities), calculated as of a specific date. The formula is total assets minus total liabilities. To find yours, add up the current value of your cash, investments, retirement accounts, real estate, and other property, then subtract your mortgage, loans, and other debts. The result is a snapshot, not a permanent number — it changes as balances, debts, and asset values shift over time.
How do I calculate my own net worth?
List every asset at its current fair market value — bank accounts, investments, retirement accounts, real estate, vehicles, and business ownership — and total them. Then list every debt at its current outstanding balance — mortgage, student loans, auto loans, credit cards, and other liabilities — and total those. Subtract total liabilities from total assets. A pen and paper or a spreadsheet is enough; no special software or advisor is required. Record the date, since the figure is accurate only as of that day.
What counts as an asset when calculating net worth?
An asset is anything of monetary value you own: cash and bank balances, brokerage and investment accounts, retirement accounts such as a 401(k) or IRA, the current market value of real estate, vehicles, and an ownership stake in a business. Value assets at their current fair market value — what they'd reasonably sell for today — rather than their original purchase price, since that price often no longer reflects true value.
What counts as a liability when calculating net worth?
A liability is a debt or financial obligation owed to someone else: a mortgage balance, student loans, auto loans, credit card balances, personal loans, and medical debt. Count liabilities at their current outstanding balance — what you'd actually have to pay to settle the debt today — not the original amount borrowed. Leaving out even a small liability will overstate your true net worth.
What is a "good" net worth for my age?
There isn't one "good" net worth figure that applies to everyone at a given age, because it depends on income, geography, family circumstances, health, and goals. Federal Reserve data shows typical (median) net worth by age group, which offers useful context, but it describes households in aggregate, not a personal target. A more useful approach is tracking whether your own net worth trends positively over time relative to your own goals.
What is the average net worth by age in the U.S.?
According to the Federal Reserve's 2022 Survey of Consumer Finances — the most recent published edition — average (mean) net worth by age of the household reference person ranged from about $183,500 for households under 35 to roughly $1.79 million for households ages 65–74, in 2022 dollars. Because the average is skewed upward by a relatively small number of very high-net-worth households, most people's actual net worth is well below the average for their age group.
What's the difference between average and median net worth?
Average (mean) net worth is the total net worth of all households in a group divided by the number of households, so it's pulled upward by a small number of very wealthy households. The median is the midpoint value when households are ranked from lowest to highest, so half have more and half have less. Because wealth is concentrated among relatively few households, the median is generally considered more representative of a "typical" household.
Is net worth the same as income?
No. Income is money earned over a period of time, such as an annual salary. Net worth is a snapshot of accumulated assets minus debts at a single point in time. A high earner with significant debt and few savings can have a lower net worth than someone with modest income who has saved consistently and paid down debt — the two figures aren't interchangeable.
Is net worth the same as savings or cash on hand?
No. Savings and cash on hand are just one component of net worth — part of your liquid assets. Total net worth also includes illiquid assets like home equity, retirement accounts, and business ownership, none of which can be quickly converted to spendable cash without delay or cost. A figure reflecting what you could access quickly is better described as liquid net worth.
What is liquid net worth, and how does it differ from total net worth?
Liquid net worth includes only cash and assets that can be converted to cash quickly without significant loss of value — checking, savings, and standard brokerage accounts, for example — minus liabilities. Total net worth includes all of that plus illiquid assets like home equity, restricted retirement accounts, and business equity. Liquid net worth is typically much lower and more relevant to short-term financial flexibility.
Can net worth be negative, and is that normal?
Yes. Negative net worth means liabilities exceed assets, and it's common — particularly among young adults, recent graduates, and people carrying student loans or other education-related debt. It isn't inherently a sign of financial trouble or poor money management; for many people it's a normal, often temporary starting point that improves as income rises and debt is paid down.
Does net worth include my house? Do I count the full value or just my equity?
Your home is included, but only as equity, not full market value. Equity is the home's current fair market value minus the outstanding mortgage balance. List the home's full market value as an asset and the mortgage as a separate liability; the difference is what actually adds to net worth.
Does net worth include retirement accounts like a 401(k) or IRA?
Yes, retirement accounts count as assets at their current market value. Keep in mind that traditional (pre-tax) balances will generally be reduced by income taxes upon withdrawal, so the stated balance isn't the same as fully spendable value. The standard calculation still uses the account's current balance, but this distinction matters when interpreting the number.
Does net worth include a car or other vehicles?
Yes, a vehicle counts as an asset at its current fair market value — not its original purchase price. Since vehicles are a depreciating asset, this value should be updated periodically using current pricing resources rather than left at the purchase price indefinitely.
How often should I calculate or update my net worth?
Most guidance suggests recalculating once or twice a year, such as annually or quarterly, rather than continuously. Checking too frequently can create noise from normal, short-term market fluctuations that don't reflect a meaningful change. A regular interval makes it easier to see a genuine trend rather than reacting to any single data point.
How can I increase my net worth over time?
Net worth generally grows through some combination of paying down debt, increasing savings and investment contributions, and letting asset values appreciate over time. Reducing high-interest debt and consistently saving are within your direct control; asset appreciation is not guaranteed. Increasing income is one lever, but it isn't the only way net worth grows.
What's the difference between gross assets and net worth?
Gross assets are the total value of everything you own, before subtracting debt. Net worth subtracts liabilities from gross assets to show what you actually own free and clear. Someone can have substantial gross assets — an expensive home, for instance — and still have modest net worth once the mortgage is subtracted.
Are net worth calculators and tracking apps accurate, and are they safe to link to my accounts?
Accuracy and safety vary by provider, so no blanket answer applies to every tool. Many apps use account aggregation to pull in balances automatically, which is convenient but introduces data-sharing considerations a spreadsheet doesn't have. Before linking accounts, review a provider's privacy policy and security practices, such as whether it uses read-only, encrypted connections, and consider its reputation and track record.
What is the Federal Reserve's Survey of Consumer Finances, and why is it cited for net worth statistics?
The Survey of Consumer Finances (SCF) is a triennial survey conducted by the Federal Reserve Board that collects detailed data on U.S. household assets, debts, and net worth. It's considered the most authoritative source on household wealth in the United States due to its scope and consistent methodology over time, which is why it's typically cited instead of private company surveys for national net worth figures.
How do self-employed people or small business owners calculate net worth if they own a business?
A business owner typically includes a reasonable estimate of their ownership stake as a personal asset — often based on the business's own assets minus its debts, or a professional valuation — while keeping the business's operating balance sheet conceptually distinct from their personal one. Business equity is generally harder to value precisely than a bank balance or publicly traded stock, since there's no daily market price for it.
Does net worth affect my ability to qualify for a loan or mortgage?
Net worth itself typically isn't the primary figure lenders use; they generally focus more on income, credit history, existing debt obligations, and specific assets like cash reserves or collateral. A strong net worth built on manageable debt often reflects the same financial habits lenders look for, but it doesn't guarantee approval or any specific outcome.
What's the difference between household net worth and individual (personal) net worth?
Individual net worth reflects one person's own assets and liabilities. Household net worth combines the assets and liabilities of everyone in a household, such as spouses or partners, into a single figure. Most published statistics, including the Federal Reserve's Survey of Consumer Finances, report net worth at the household level, so comparing your individual figure directly to those statistics may not be an apples-to-apples comparison.
Sources
Federal Reserve Board — Survey of Consumer Finances (SCF)
Federal Reserve Board — Changes in U.S. Family Finances from 2019 to 2022: Evidence from the Survey of Consumer Finances (October 2023)
Federal Reserve Board — 2025 Survey of Consumer Finances announcement (February 2025)
Federal Reserve Board — Distributional Financial Accounts (DFA)
Consumer Financial Protection Bureau — consumerfinance.gov (general consumer financial data-rights guidance; verify current Section 1033 rulemaking status directly)
Congressional Research Service, Library of Congress — Access to Consumer Financial Data: Open Banking and the CFPB's Section 1033 Rule
Federal Deposit Insurance Corporation — fdic.gov (standard deposit insurance coverage information)
National Credit Union Administration — ncua.gov (share insurance coverage information)
Internal Revenue Service — irs.gov (general fair market value and cost basis definitions)
Bureau of Labor Statistics — bls.gov (Consumer Price Index and inflation context)
Conclusion
Net worth is a straightforward calculation — total assets minus total liabilities — but it's only a snapshot in time, not a complete measure of financial health or personal worth. It excludes income stability, cash flow, health, insurance coverage, and future earning potential. Negative or below-benchmark net worth is common, especially early in adulthood, and isn't by itself a sign of failure. National figures like those from the Federal Reserve's Survey of Consumer Finances are useful context, not a personal target, and the median generally tells a more representative story than the average. Because individual circumstances vary widely, track your own net worth trend over time, and consult a qualified, fee-only financial planner for individualized guidance — use this guide as a starting framework, not a final word.
Recommended Articles
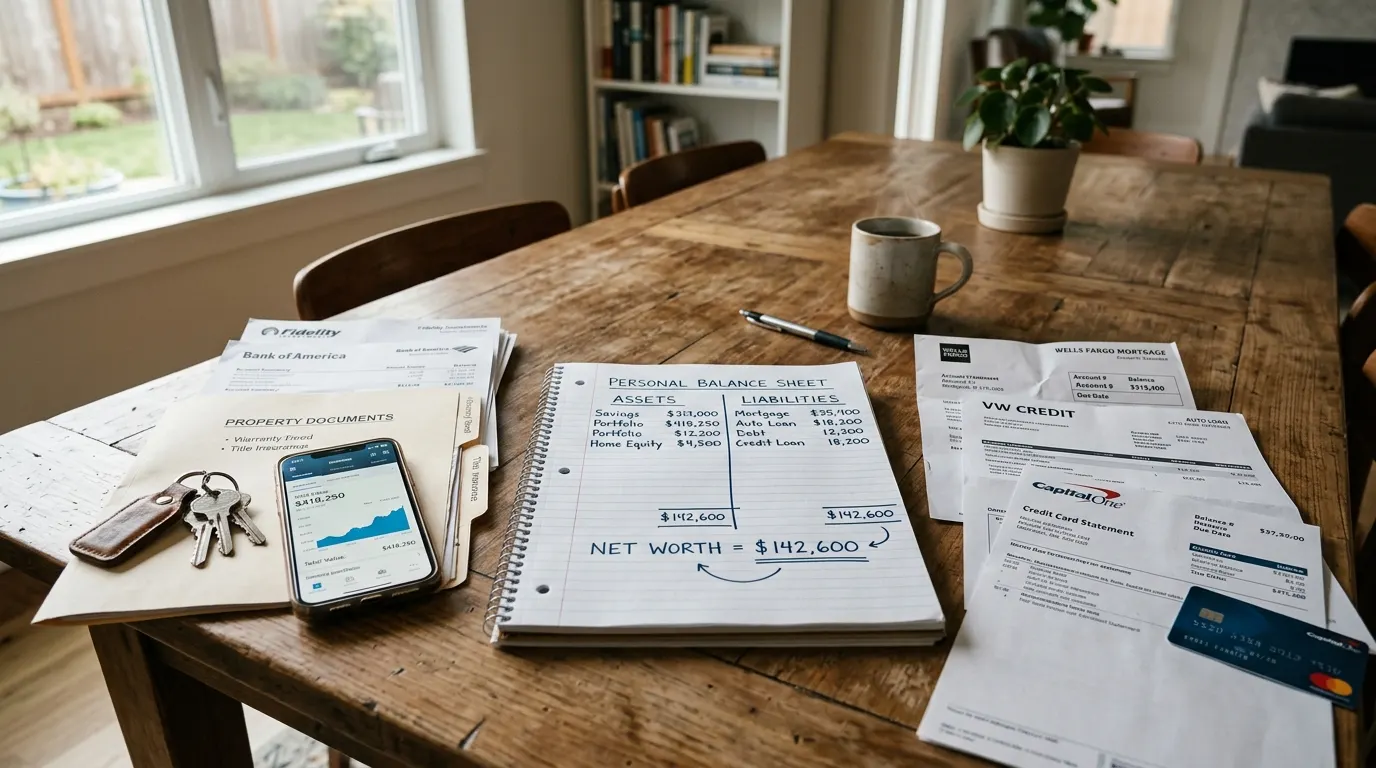
Assets vs. Liabilities: A Simple Guide to Net Worth
Learn the difference between assets and liabilities, how to calculate net worth, examples, and why a house or car can be both.
What Is Open Banking? How It Works, Benefits & Risks
Learn what open banking is, how it works, benefits, risks, API access, and U.S. Section 1033 rules for sharing financial data securely.